Buying a home
First home or next home: understand your budget, down payment and next steps.
Explore buying a home
Opening doors. Building futures.
Personalized mortgage advice for buying, renewing, refinancing or investing. Clear options, plain language and service built around you.
Gabriela Masic, Mortgage Associate · Breezeful Inc., Mortgage Brokerage
Mortgage solutions for every stage
A mortgage is more than a rate. I help you understand your choices and find a path that fits your goals.
First home or next home: understand your budget, down payment and next steps.
Explore buying a homeStart early, compare terms and make an informed decision before your renewal date.
Plan your renewalReview your mortgage and explore options for renovations, cash flow or consolidating debt.
Review refinancingFinancing for a rental property or a home with a rental unit.
Discuss your plansHow lenders assess income when you own a business or work for yourself.
Explore your optionsMortgage options and documents that may apply to newcomers.
Start a conversationFinancing for cottages, recreational and rural properties, and vacant land.
Explore your optionsWhether it’s your first home or your next one, know your budget before you fall in love with a property.
Buying a home goes more smoothly when the financing is sorted out early. A pre-approval tells you roughly how much a lender may lend and can hold a rate for a period of time while you shop. It isn’t a final approval: the lender still has to approve the property and confirm your documents.
In Canada, the minimum down payment is 5% of the first $500,000 of the price and 10% of the portion above $500,000, for homes under $1.5 million. Homes at $1.5 million or more need at least 20% down. With less than 20% down, the mortgage must be insured against default, and the insurance premium is usually added to the mortgage. First-time buyers and buyers of newly built homes can choose an amortization of up to 30 years on an insured mortgage.
Don’t forget closing costs: New Brunswick’s real property transfer tax, legal fees, a home inspection and adjustments typically add a few percent to the price. See the closing costs guide.
Lenders look at your housing costs and total debts compared with your gross income, calculated at the stress-test rate. The affordability calculator gives a first estimate, and the GDS & TDS calculator shows the ratios lenders check.
Usually yes, from an immediate family member, with a signed gift letter confirming it doesn’t have to be repaid. Lenders will want to see the funds in your account before closing.
Insurance the lender requires when you put less than 20% down. It protects the lender, not you. The premium is a percentage of the loan, from 2.80% to 4.00% for down payments between 5% and 19.99%, and is normally added to the mortgage.
Often yes. First-time buyers may be able to use the RRSP Home Buyers’ Plan and a First Home Savings Account. See the first-time buyer guide.
Payment, default insurance, total interest and stress-test payment.
Estimate the price range lenders may approve, at the stress-test rate.
Estimate New Brunswick’s real property transfer tax at closing.
Down payment, programs, pre-approval and closing, step by step.
Your renewal is a chance to rethink your mortgage, not just to sign the letter your lender sends.
Your lender will usually send a renewal offer a few weeks or months before your term ends. Signing it is easy, but the first offer isn’t always the most competitive one, and it may not be the right term or rate type for the next few years.
Starting about four months before your renewal date gives time to compare offers, hold a rate with another lender and, if it makes sense, switch. Switching at renewal usually carries no prepayment penalty because your term has ended, though there can be legal or discharge fees, which some lenders cover.
Since November 2024, federal rules generally no longer require you to pass the stress test again if you switch lenders at renewal without increasing your mortgage amount or amortization. This makes it easier to shop around.
About 120 days before your renewal date. Many lenders will hold a rate for around that long.
A lender will check your credit, which is a small, temporary effect. Applications made close together for the same purpose usually have a limited impact.
Depending on your lender and mortgage terms, you may be renewed automatically on the lender’s terms, or your mortgage may become an open mortgage at a higher rate. Read your renewal letter carefully.
Sometimes. Extending it lowers your payment but increases total interest, and may require qualifying again. Let’s look at the numbers together.
Use your home equity thoughtfully, for renovations, consolidating higher-interest debt or other goals.
A refinance replaces your current mortgage with a new one, often for a larger amount. In most cases you can borrow up to 80% of your home’s appraised value, minus what you still owe. A refinance means qualifying again, including the stress test.
Refinancing in the middle of a term usually triggers a prepayment penalty, which can be large on a fixed-rate mortgage. Sometimes waiting until renewal, adding a secured line of credit, or blending your rate with your current lender works out cheaper. The right answer depends on the numbers.
Typically up to 80% of the appraised value, less your current mortgage balance and any other secured debt.
It can lower your monthly payments, but spreading short-term debt over a long amortization can cost more in total interest. We’ll compare both.
It depends on your lender’s method, so ask your lender for the exact figure in writing. I can help you weigh it against what you’d save by refinancing.
From a home with a basement suite to a small multi-unit building.
Lenders treat rental property differently from the home you live in. If you will not live in the property, the minimum down payment is generally 20% and mortgage default insurance isn’t available. If you will live in one unit of a property with up to four units, lower down payment options may apply.
Lenders also differ in how much of the rent they count. Some add part of it to your income; others subtract it from the property’s costs. That difference can change how much you qualify for, which is why comparing lenders matters for investors.
Usually 20% if you won’t live there. Owner-occupied properties with up to four units can qualify with less.
Often yes, by refinancing or using a secured line of credit. Interest deductibility is a tax question, so check with your accountant.
Business owners, contractors and commission earners can get a mortgage. It takes the right documents and the right lender.
Lenders usually look at your income over the last two years, based on your tax returns and Notices of Assessment. If you write off a lot of expenses, your taxable income may be lower than what you actually earn, which can limit how much a lender will approve.
Some lenders have programs that consider a reasonable stated income for established businesses, and alternative lenders offer more flexibility, often at a higher rate. Knowing which lender fits your situation before you apply saves time and avoids unnecessary credit checks.
Many lenders want two years. Some will consider less if you work in the same field you were employed in before.
Possibly, through stated-income or alternative lender programs. Rates and down payment requirements are usually higher, so we’ll weigh the cost.
A limited Canadian credit history doesn’t have to stop you from buying a home.
Several lenders have programs for permanent residents and some work permit holders who have recently arrived. They may accept alternative proof of credit, such as rent payment history or a reference letter from a bank in your home country, and may allow down payment funds from abroad when they are properly documented.
A federal law restricts many non-Canadians from buying residential property in Canada until January 1, 2027, with exceptions, for example for permanent residents and some work permit holders. Check whether it applies to you before making an offer.
It helps, but newcomer programs may accept alternatives. Opening a Canadian credit card early and paying it in full each month builds history.
Often yes, if you can document where it came from and it’s in a Canadian account before closing. Lenders may want to see it held for a period of time.
Cottages, rural homes and vacant land are financed differently from a typical home. Knowing the rules before you make an offer can save you a lot of stress.
Lenders look closely at the property itself: how you get to it, whether it can be lived in year-round, its water and septic systems, and how easy it would be to sell. These details decide which lenders will finance it, how much down payment you need and what rate you’ll pay.
Lenders usually sort cottages into two groups:
Cottages on leased land, islands or properties without road access are harder still, and are often financed by credit unions or alternative lenders.
For a home in the country, lenders will look at the well and septic system, road access, and the size of the lot. Some lenders count only the house and part of the land when they value a large acreage, so the financing can come in lower than the purchase price suggests. Water tests and a septic inspection are usually conditions of the mortgage.
Buying land with no house on it is one of the harder purchases to finance. Fewer lenders offer land mortgages, and they typically ask for a much larger down payment, often 25% or more, with a shorter amortization and a higher rate. Serviced lots with road access and utilities nearby are easier to finance than raw land. If you plan to build, a construction mortgage may be the next step.
If you already own a home, refinancing it or using a home equity line of credit can sometimes fund a cottage or land purchase on better terms, because the loan is secured by your main home. The extra payment still counts in your debt ratios, so it’s worth comparing both routes.
Sometimes. A four-season cottage you use yourself may qualify for an insured mortgage with as little as 5% down. Seasonal cottages and properties you plan to rent out usually need more.
Yes, but if renting is the main purpose, lenders treat it as an investment property, which usually means at least 20% down. Tell your lender how you plan to use it.
Land is harder for a lender to sell if a borrower can’t pay, and it produces no rent or housing value until something is built. That’s why lenders ask for a larger down payment and charge more.
About
Licensed in New Brunswick with Breezeful Inc., Mortgage Brokerage.
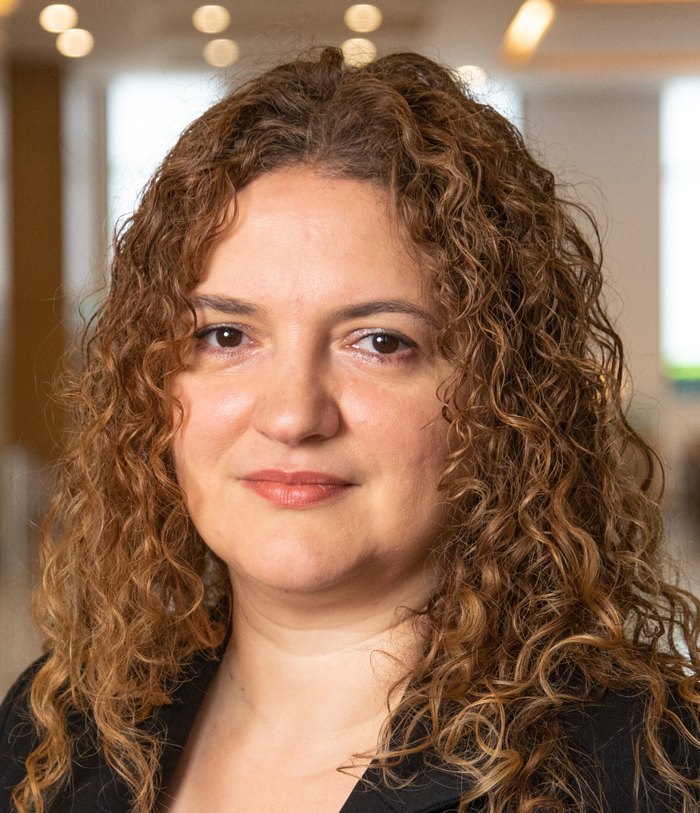
Hi, I’m Gabriela Masic.
I’m a Mortgage Associate licensed by the Financial and Consumer Services Commission of New Brunswick (FCNB), working with Breezeful Inc., a Canadian mortgage brokerage. I help people across New Brunswick buy their first home or their next one, renew or refinance an existing mortgage, and finance rental property.
My career has been built around helping organizations and individuals make informed financial decisions. My background as a Senior Financial Analyst gives me a different perspective on mortgage financing: I combine analytical expertise with a genuine passion for helping people achieve homeownership.
I also know the process from the other side of the table. As a buyer myself, I understand the questions, the paperwork and the big decisions involved, and I’m familiar with land and vacation properties, which lenders treat differently from a typical home. I know how much it helps to have a knowledgeable, trustworthy agent in your corner.
A mortgage is one of the biggest financial commitments most people make, yet it’s often chosen in a hurry. Every client’s situation is different, so I take the time to understand your goals and slow the decision down just enough to make it a good one. I’ll explain the trade-offs (rate type, term, prepayment options, penalties and total cost) in plain language, and guide you through the process from start to finish.
Working with Breezeful Inc. gives me access to a wide network of lenders, so I’m not limited to one bank’s products. I can explore a broad range of solutions and match you with options that truly fit your needs, not just the easiest or most common path. You’ll see the choices side by side, understand why one fits better than another, and make the decision yourself.
My commitment is simple:
Whether you’re a first-time home buyer, an experienced homeowner or a real estate investor, my goal is to make your mortgage experience smooth, transparent and as stress-free as possible.
Gabriela Masic, Mortgage Associate, FCNB licence no. 260060808
Breezeful Inc., Mortgage Brokerage, FCNB licence no. 230013022
You can confirm both licences on the FCNB licence search.
See also Gabriela’s profile on Breezeful (opens in a new tab).
Plan with confidence
Quick estimates to help you plan. The calculators run in your browser; nothing you type is saved or sent.
Illustrative estimate only, not a rate quote, approval or commitment to lend. Assumes the rate stays the same for the full amortization; fixed rates compounded semi-annually, variable rates monthly. Insurance premiums use CMHC’s published schedule and may differ by insurer. Excludes property tax, insurance, heating and closing costs.
Want a second opinion on the numbers? Get in touch.
Uses common lender limits of 39% (housing costs) and 44% (all debts) of gross income, calculated at the stress-test rate. Lenders apply their own policies; this is not a pre-approval.
Lenders compare your housing costs (mortgage payment, property tax, heating and half of any condo fees) with your gross income. This is the gross debt service (GDS) ratio, typically capped at 39%. They also add your other debt payments to get the total debt service (TDS) ratio, typically capped at 44%. Both are calculated at the stress-test rate.
Your credit history, the property and each lender’s policies also matter. Treat this as a starting point, then talk to me about a pre-approval.
Includes Service New Brunswick registration fees for the deed and the mortgage ($85 each). Estimate only. Confirm the amount with your lawyer before closing.
New Brunswick charges real property transfer tax when a property changes hands and the deed is registered. The tax is 1% of the greater of the purchase price and the property’s assessed value. Your lawyer collects it on closing.
Budget for the other closing costs too: legal fees, title insurance, a home inspection, property tax adjustments and moving costs. See the closing costs guide.
Uses common lender limits of 39% (GDS) and 44% (TDS) for insured mortgages, calculated at the stress-test rate. Some lenders allow different limits depending on credit and mortgage type. Estimate only, not a pre-approval.
Before approving a mortgage in New Brunswick or anywhere in Canada, lenders check two debt service ratios: your gross debt service (GDS) ratio and your total debt service (TDS) ratio. Use the calculator above to see where yours stand, then read on to understand what the numbers mean.
Your GDS ratio is the share of your gross (before-tax) income needed to cover your housing costs:
GDS = housing costs ÷ gross income
Your TDS ratio adds all your other debt payments to those housing costs, such as car loans, personal loans, credit cards, lines of credit and support payments.
TDS = (housing costs + other debt payments) ÷ gross income
These two ratios tell you, and your lender, how much you can afford to borrow. They are a key part of every mortgage pre-approval and are calculated at the mortgage stress-test rate, not just your contract rate.
For insured mortgages, the usual limits are 39% for GDS and 44% for TDS. If your ratios are over these limits, the most common fixes are saving a larger down payment, paying down debts, adding a co-applicant or choosing a less expensive home.
For the most choice of lenders and rates, aim for a GDS below 35% and a TDS below 42%.
If your ratios are higher, you still have options. Through Breezeful’s wide network of lenders, mortgages can be arranged with GDS and TDS ratios of up to 45% and 47%, and up to 50% for both in certain situations, such as with a down payment of 35% or more.
Not sure where you stand? Book a free conversation and I’ll review your numbers with you and explain your options.
Areas served
Meetings by appointment, in person, by phone or by video.
Saint John, Rothesay, Quispamsis and Grand Bay-Westfield.
Whether you’re buying your first home in Saint John, moving up in Rothesay or Quispamsis, or renewing a mortgage in Grand Bay-Westfield, I can help you compare options from multiple lenders and understand the total cost before you commit.
Moncton, Dieppe, Riverview and Shediac.
Greater Moncton draws first-time buyers, families relocating for work and newcomers to Canada. Whatever brings you here, I can help you understand your budget, compare lenders and plan for closing costs.
Fredericton, Oromocto and New Maryland.
From first homes near the city to renewals for long-time homeowners, I help Fredericton-area clients compare options and understand the trade-offs before they sign.
Resources
Plain-language guides to help you prepare. Rules change, so confirm details before you act.
The steps, programs and costs to know before you buy your first home.
Last reviewed: November 2026 · Written by Gabriela Masic, Mortgage Associate
Start with what you’re comfortable paying each month, not just the maximum a lender might approve. Lenders qualify you at the stress-test rate, so try the affordability calculator, then the payment calculator.
The minimum is 5% of the first $500,000 and 10% of the portion above, for homes under $1.5 million. Federal programs can help first-time buyers:
Check the rules and your eligibility on Canada.ca before you rely on them.
A pre-approval estimates what a lender may lend and can hold a rate while you shop. Have your ID, proof of income and proof of down payment ready.
With less than 20% down, your mortgage must be insured. The premium (2.80%–4.00% of the loan, depending on your down payment) is usually added to the mortgage. First-time buyers can choose up to a 30-year amortization on an insured mortgage, which lowers the payment but increases total interest.
Make your offer conditional on financing and inspection where possible. Once accepted, the lender approves the property, often with an appraisal, and issues a commitment.
Plan for New Brunswick’s real property transfer tax, legal fees, title insurance, inspection and adjustments. See the closing costs guide.
Next step: book a free conversation and we’ll map out your plan.
Why lenders qualify you at a higher rate than the one you’ll pay.
Last reviewed: November 2026 · Written by Gabriela Masic, Mortgage Associate
Federally regulated lenders must check that you could still afford your payments if rates rose. They qualify you at the higher of your contract rate plus 2% or 5.25%, even though you’ll pay your actual rate.
If your rate is 4.50%, you’re qualified at 6.50%. On a $360,000 mortgage over 25 years, that’s roughly the difference between a payment of about $1,990 and about $2,410 a month. Your income and debts must support the higher figure. Try the payment calculator to see your own numbers.
Since November 2024, a straight switch to a new lender at renewal, with no increase in the amount or amortization, generally doesn’t require passing the stress test again.
Source: OSFI – minimum qualifying rate.
The costs that come due on or before closing day, beyond your down payment.
Last reviewed: November 2026 · Written by Gabriela Masic, Mortgage Associate
Lenders usually want to see that you have about 1.5% of the purchase price available for closing costs on top of your down payment. Actual costs vary, so here’s what to plan for.
1% of the greater of the purchase price and the assessed value, collected by your lawyer on closing. Registering the deed and the mortgage with Service New Brunswick costs $85 each. Use the transfer tax calculator for an estimate; your lawyer will confirm the exact amount before closing.
Your lawyer handles the title search, registration of the deed and mortgage, and the transfer of funds. Ask for a written quote that includes disbursements and registration fees.
Often required by the lender; usually a few hundred dollars.
An inspection is strongly recommended before your offer becomes firm. Some lenders also require an appraisal, which may be paid by you or the lender.
If the seller prepaid property tax or utilities for a period after closing, you’ll reimburse them for your share.
Home insurance (required by the lender before funding), moving costs, utility hook-ups and any immediate repairs.
Note: if your mortgage is insured, the default insurance premium is usually added to the mortgage rather than paid at closing.
Plain-language definitions of the terms you’ll hear most often.
Last reviewed: November 2026 · Written by Gabriela Masic, Mortgage Associate
Good questions to ask
Ideally before you start making offers, or about four to six months before your renewal date. An early conversation helps you understand your budget, the documents you’ll need and the options available.
A bank can only offer its own products. As a Mortgage Associate with Breezeful Inc., Mortgage Brokerage, I can compare options from the lenders Breezeful works with, including banks, credit unions and lenders that only work through brokers. You can see the choices side by side: the rate, but also prepayment options, penalties, portability and total cost.
A broker can also help when your situation doesn’t fit a standard box, for example self-employed income, a recent move to Canada or a rental property.
Often there are competitive options, but no one can promise a lower rate. Rates depend on your credit, down payment, income, the property and the market on the day you apply. What I can do is show you what’s available from several lenders so you can compare, and point out terms that matter as much as the rate, like the penalty for breaking the mortgage early.
A first conversation is free and there’s no obligation. For most residential mortgages in New Brunswick, the lender pays the brokerage when the mortgage closes, so there is no fee to you. Some private, alternative or commercial mortgages may carry a fee. If a fee would apply to your situation, it will be explained in writing before you sign anything.
Clients buying, renewing, refinancing or investing in property anywhere in New Brunswick, including self-employed borrowers and people who are new to Canada.
A general idea of your goals and timeline, your income, monthly debts and how much you have for a down payment. Please don’t send documents by email. When you’re ready, you can apply online (opens in a new tab) and upload them securely.
No. It’s an estimate based on the numbers you enter. Approval depends on the lender’s review of your income, credit, debts, down payment and the property.
Lenders look at five main things:
Lenders measure affordability with two debt service ratios. GDS (gross debt service) is your housing costs (mortgage payment, property tax, heating and half of any condo fees) as a share of your gross income. TDS (total debt service) adds all your other debt payments. For insured mortgages the usual limits are 39% GDS and 44% TDS, calculated at the stress-test rate. Some lenders allow different limits depending on credit and the type of mortgage.
Better credit gives you more choice and usually better rates, but there are options across a range of credit histories. For an insured mortgage (less than 20% down), at least one borrower generally needs a credit score of 600 or higher, and individual lenders may set their own minimums. If your credit is bruised, alternative lenders may help in the short term while you rebuild.
Checking your credit for a mortgage application usually has only a small, temporary effect on your score. You can check your own report for free with Equifax Canada and TransUnion Canada.
A pre-qualification is a quick estimate of what you might borrow, based on information you provide. Nothing is verified.
A pre-approval goes further: a lender reviews your credit and documents and can hold a rate for you, usually for 90 to 120 days. It gives you a clearer budget when you shop, but it isn’t a final approval. The lender still has to approve the specific property, and confirm that nothing in your finances has changed.
Documents often requested for a pre-approval include:
Yes. Lenders want to see that your income is steady and can be verified, which usually means about two years of self-employment history. Documents commonly requested include:
If your taxable income is low because of business write-offs, some lenders have programs that look at your business more broadly. These can carry a slightly higher rate or need a larger down payment.
Often, yes. Several lenders and the mortgage insurers have programs for newcomers. Even if you haven’t built a Canadian credit history yet, they may accept alternatives such as a letter of reference from your bank abroad or a history of rent and utility payments. The required down payment and documents depend on your situation and the program, so it’s worth talking early, before you start house hunting.
If the home you’re buying has a rental unit, such as a basement apartment or the other side of a duplex, many lenders will count part of the expected rent toward your qualifying income or use it to offset the mortgage costs. How much they count varies by lender and property type. You’ll usually need a lease or an appraiser’s estimate of market rent.
A decline from one lender doesn’t mean every lender will say no. Lenders have different rules for income, credit and property types. Options can include other banks and credit unions, lenders that only work through brokers, and alternative or private lenders. Alternative and private mortgages usually cost more and may carry fees, so they are often used for a short term while you improve your credit or income. If one makes sense for you, I’ll explain the full cost and an exit plan up front.
It’s best to wait until after your mortgage closes. Lenders can re-check your credit and employment before funding, and a new car loan, new credit card, large purchase on credit or a job change can affect your approval. If something changes, tell me right away so we can deal with it before closing.
In Canada the minimum is 5% of the first $500,000 of the price and 10% of the portion above that, up to $1.5 million. At $1.5 million or more, and for most rental properties you won’t live in, the minimum is 20%. With less than 20% down you’ll also need mortgage default insurance.
If your down payment is less than 20%, your mortgage must be insured against default with CMHC, Sagen or Canada Guaranty. The insurance protects the lender, not you, but it is what makes a smaller down payment possible.
The premium is a percentage of the mortgage amount, from about 2.8% to 4% depending on the size of your down payment. A 30-year amortization adds a small surcharge. The premium is usually added to your mortgage rather than paid at closing. The maximum amortization on an insured mortgage is 25 years, or 30 years for first-time buyers and purchases of newly built homes.
Two federal programs help first-time buyers save a down payment:
You can use both for the same purchase, and each buyer in a couple can use their own. Eligibility rules apply. Check the details on the Canada Revenue Agency website or with your tax advisor.
Plan for closing costs of about 1.5% to 4% of the purchase price. In New Brunswick these include the real property transfer tax, legal fees, title insurance, a home inspection, any appraisal fee, and adjustments for property tax or fuel already paid by the seller. The Closing Costs in New Brunswick guide explains each one.
To qualify, you need to show you could still afford your payments at a higher rate: the greater of your contract rate plus 2% or 5.25%. It applies to most new mortgages and refinances. The Mortgage Stress Test, Explained guide walks through an example.
A fixed rate stays the same for the whole term, so your payment is predictable.
A variable rate moves with the lender’s prime rate. With some variable mortgages your payment changes when prime changes. With others the payment stays the same and the share going to interest changes instead. Variable rates can be lower at times, and the penalty for breaking one is usually smaller, but you take on the risk that rates rise. The right choice depends on your budget, how long you plan to keep the mortgage and how comfortable you are with change.
An open mortgage can be paid off in full or in part at any time without a penalty, but it has a higher rate and usually a short term. It suits someone who expects to sell or pay off a large amount soon.
A closed mortgage has a lower rate, but limits how much extra you can pay each year and charges a penalty if you break it early. Most borrowers choose a closed mortgage.
The amortization is the total time it would take to pay off the mortgage, often 25 years. The term is the length of your current contract with the lender, commonly 1 to 5 years. When the term ends you renew, often at a new rate, until the mortgage is paid off.
Most closed mortgages let you pay down extra each year without a penalty, for example a yearly lump sum of 10% to 20% of the original amount, or a higher regular payment. The exact limits vary by lender and are worth comparing, because they can save you a lot of interest over time.
If you pay off a closed mortgage early, refinance or switch lenders before the term ends, the lender charges a prepayment penalty.
The IRD is roughly the interest the lender loses because today’s rates are lower than yours, for the time left in your term. Lenders calculate it differently, and on a fixed-rate mortgage it can be several thousand dollars. Your lender can give you an exact figure, and comparing penalty terms before you sign is one of the most useful things a broker can help with.
Many mortgages are portable, which means you can move the balance, rate and term to a new home without a penalty, subject to the lender approving the new property and your finances. If you need more money, some lenders will “blend” the old rate with a new rate on the extra amount. Some mortgages are also assumable, which means a qualified buyer can take over your mortgage. These features vary by lender, so check them before you sign.
Start looking about four to six months before your renewal date. Your lender will send a renewal offer, often only a few weeks before the date. It isn’t always its best rate, and signing it without comparing can cost you. You can renew with your lender, negotiate, or switch to another lender at renewal without a penalty. Many lenders will hold a rate for up to 120 days.
Usually not. If you switch at renewal without increasing your mortgage amount or amortization (a “straight switch”), federally regulated lenders are not required to apply the stress test. You’ll still need to provide documents and be approved by the new lender. Adding money or extending the amortization turns it into a refinance, which is fully re-qualified.
Refinancing replaces your mortgage with a new one, usually to borrow against your home equity. People refinance to consolidate higher-interest debt, pay for renovations, or help with another purchase. You can generally borrow up to 80% of your home’s value. Refinancing before your term ends usually means a prepayment penalty, so it’s worth comparing the total cost against alternatives such as a home equity line of credit or a second mortgage.
New to mortgage terms? See the mortgage glossary. Rules and limits change, so we’ll confirm what applies to you before you decide.
Ready for the next step?
Book a time that suits you, call or email me directly, or start your application online whenever you’re ready.
Contact
Mortgage Associate
Breezeful Inc., Mortgage Brokerage
View my Breezeful profile (opens in a new tab)
(506) 409-2244
gabriela.masic@teambreezeful.com
By appointment. Serving clients across New Brunswick in person, by phone or by video.
Evening & Weekend Appointments Available.
Book an appointment (opens in a new tab)Apply online (opens in a new tab)
Please don’t send ID, bank statements or tax documents by email. If you go ahead, you’ll upload them securely through the online application (opens in a new tab).
Legal
Last updated: November 2026
Gabriela Masic, Mortgage Associate, provides mortgage brokering services in New Brunswick through Breezeful Inc., Mortgage Brokerage. Protecting your personal information is part of earning your trust. This policy explains what information is collected, how it is used and protected, and the choices you have. We follow Canada’s Personal Information Protection and Electronic Documents Act (PIPEDA).
PIPEDA is built on ten fair information principles. Here is how we apply each one.
Breezeful Inc., Mortgage Brokerage is the organization accountable for personal information handled in connection with the mortgage services described on this website, including information shared with lenders and others to deliver services you request. Gabriela Masic is responsible for this website and for information you share with her directly.
We tell you why we need your information before or when we collect it, usually during our first conversation or in your mortgage application.
We collect, use and share your information only with your consent, except where the law allows otherwise. Consent may be given in writing, verbally or through your actions, for example by submitting an application. You can withdraw consent at any time, subject to legal and contractual limits, although this may limit the services we can provide.
We collect only the information needed to arrange your mortgage, by fair and lawful means.
Your information is used only for the purposes you agreed to. Records of mortgage brokering services are kept for at least seven years, as required in New Brunswick, and then securely destroyed.
We keep your information as accurate and up to date as needed for its purpose. Please let us know if anything changes or needs correcting.
Your information is protected with security measures suited to its sensitivity. Applications and documents are handled on Breezeful’s secure platform, never by ordinary email.
This policy is always available on this website, and we will gladly answer questions about how your information is handled.
You can ask to see the personal information held about you and how it has been used or shared. Access is refused only where the law permits, and we will explain why.
If you have a concern about how your information has been handled, you can raise it with us using the contact details below.
To respond to your questions, to assess your options and arrange your mortgage, to keep the records required by the Financial and Consumer Services Commission (FCNB), and, if you agree, to contact you before your renewal. We will not use your information for a new purpose without telling you and asking for your consent.
We never sell your personal information.
This website does not use cookies, analytics tools, advertising pixels or other tracking technologies. Like most websites, the company that hosts it may keep standard technical logs (such as IP address and browser type) for security and to keep the site running. These logs aren’t used to identify you.
This website links to Breezeful Inc., government and other websites. Their content and privacy practices are governed by their own policies.
You won’t receive marketing messages unless you ask for them, and you can opt out at any time.
To ask a question, request access to or correction of your information, or make a complaint, contact Gabriela Masic at gabriela.masic@teambreezeful.com or (506) 409-2244. For information held on Breezeful’s platform, you may also contact Breezeful Inc. directly. If you’re not satisfied with the response, you may contact the Office of the Privacy Commissioner of Canada (opens in a new tab).
We may update this policy, for example if this website’s practices change. The date at the top shows when it was last updated.
Last updated: November 2026
Gabriela Masic, Mortgage Associate, licensed by the Financial and Consumer Services Commission (FCNB), licence no. 260060808.
Breezeful Inc., Mortgage Brokerage, licensed by the Financial and Consumer Services Commission (FCNB), licence no. 230013022.
Prospect Key Mortgages is a business name of Breezeful Inc., Mortgage Brokerage. Mortgage brokering services are offered in New Brunswick only. Verify licences with FCNB.
Before you sign a mortgage commitment or agreement, you will receive the written disclosures required in New Brunswick, including any fees you would pay, how the brokerage is compensated and any relationships or conflicts of interest. All mortgages are subject to lender approval. We cannot guarantee approval, a particular rate or terms.
Content on this website is general information, not financial, legal or tax advice for your situation. Rules, rates and programs change. Calculator results are estimates based on the figures you enter and the assumptions described with each calculator; they are not a rate quote, a pre-approval or a commitment to lend.
Links to Breezeful, government and other websites are provided for convenience. We aren’t responsible for their content or privacy practices.
If you have a concern, please contact Gabriela first. If it isn’t resolved, you may contact Breezeful Inc.’s principal broker [Breezeful to provide contact details]. You may also contact the Financial and Consumer Services Commission (FCNB).
Text and design © Gabriela Masic. Photographs are used under licence from their owners.